Commercial mortgage: how to buy an office and assess bank terms
A commercial mortgage is a loan used to purchase non-residential property, secured by property, usually the asset being acquired. It can enable you to buy an office without paying the entire purchase price from your own funds upfront. Financing eligibility depends on the buyer, the property's characteristics and the terms of the particular bank.
For business owners considering office financing in Russia, the key question is not “where is the lowest rate?” but “does this loan suit the office, and can the business afford the full cost of ownership?” Below is a step-by-step assessment, from choosing the borrower and calculating the initial budget to obtaining property approval, paying the seller and registering the transaction.
The cover is a conceptual illustration of office purchase financing, not a photograph of the F-375 property.
Who can obtain a commercial mortgage?
The Russian market includes lending programmes for individuals, individual entrepreneurs and legal entities. However, similar product names do not mean identical terms. A retail mortgage for non-residential premises and a loan to an operating business can differ substantially in their requirements for the borrower, collateral, seller and purpose of the purchase.
For an individual, a bank may assess verified income and existing commitments. When lending to an individual entrepreneur or a company, it also considers business operations, financial statements, cash flows and ownership structure. Guarantees and additional security depend on the programme and the bank's decision: neither their necessity nor their absence should be assumed in advance.
First establish who will own the property and who will borrow, then look for financing. A company purchasing premises is not equivalent to its founder buying them with personal funds. These options affect documentation, office use and the risks borne by the parties in different ways. Our separate guide explains who should own commercial property: an individual, an individual entrepreneur or an LLC.
Which office can you buy? Check the collateral requirements
A bank is not obliged to finance every property marketed as an office. A programme may restrict location, floor level, registered use, completion status, seller type or existing encumbrances. Even if the buyer has preliminary approval for the required amount, the chosen office still needs approval.
For an office in a mixed-use complex, a high-floor property or a multi-level penthouse, checking eligibility under the bank's programme in advance is particularly important. A marketing description cannot replace registered property information. The bank will examine the documents and characteristics of the specific collateral.
- Establish whether the offer comprises a single registered property or several premises with separate cadastral numbers.
- Compare the registered use and area in the documents with the actual layout and intended use.
- Provide the bank with details of existing charges, agreements granting use of the premises and any other restrictions, where applicable.
- Find out whether additional security will be required if the office being purchased is insufficient collateral for the chosen financing.
It is sensible to make these checks before incurring non-refundable costs. In preliminary discussions with the seller, separately agree what will happen if the bank rejects the property or changes the loan amount.
Mortgage, secured loan or instalments: what is the difference?
There are several possible ways to finance an office purchase. Compare the source of funds, security, payment timetable and buyer's obligations, not just product names. Seller-financed instalments are available only if the parties actually agree their terms; an office being offered for sale does not in itself imply this option.
If an existing property serves as collateral, the security over it can also be registered as a mortgage. The table compares purchase-financing arrangements, not mutually exclusive legal definitions. A bank product's name alone does not disclose all the contract terms.
| Option | How it works | What the buyer should check |
|---|---|---|
| Commercial mortgage | A loan to acquire property; the property being purchased usually serves as collateral. | Whether the office qualifies, how much the bank will finance and when the seller will receive payment. |
| Loan secured against existing assets | Security is provided by assets already owned by the borrower or another security provider. | Whether the loan may fund an office purchase and which assets will be at risk if obligations are breached. |
| Seller-financed instalments | The purchase price is paid in instalments according to a timetable agreed by the parties. | When title transfers, the seller's security, liability and the consequences of late payment. |
A smaller initial payment does not necessarily mean a lower total cost or a safer transaction. Compare the options using a consistent budget and separately assess restrictions on using and subsequently selling the office.
Why two approvals are needed: the buyer and the property
The transaction involves two distinct questions: can the buyer service the loan, and will the bank accept the selected property as collateral? These can be described as borrower approval and property approval. The review sequence depends on the bank, but a positive answer to one question does not resolve the other.
A preliminary decision may be conditional on income verification, no material changes in existing commitments, further documents or valuation results. Check how long the decision is valid and the circumstances in which the bank may revise its offer before releasing the funds.
Ask the bank's representative to set out the remaining steps and approvals in writing. Pay particular attention when a price has already been agreed with the seller but the valuation and final loan terms are still unknown. Reservation payments, advances and earnest-money deposits should not be assumed to be protected automatically if the bank declines the loan: the consequences depend on the documents signed.
The down payment and the full purchase budget
Your own funds are needed for more than the down payment. The budget may include valuation, transaction and payment-processing costs, insurance required by the programme, document checks, preparing the premises for use and a liquidity reserve. The components and amounts of these costs must be checked for your specific transaction.
Do not confuse the sale price with the amount on which the bank bases available financing. Depending on the programme, the relevant figure may be the appraised value, contract price or another agreed measure. If the bank's valuation is below the seller's price, the buyer may need more of their own funds than the loan's marketing description suggests.
Before commissioning a valuation report, confirm whether the bank accepts the chosen valuer, what scope of work it requires and how long the report will remain valid for its review. If the valuation differs from the seller's price, ask for an explanation, but do not budget on the assumption that it will be revised. The principles are covered in our separate guide, “How to value commercial property”.
For planning purposes, it is useful to split the budget into three parts:
- Funds required for completion: the difference between the purchase price and the loan actually available, plus associated costs.
- Post-purchase costs: operation, maintenance, mandatory payments, equipment and any work needed in the office.
- A reserve: money remaining in the business after paying for the property and the costs of making it ready for use.
VAT and other tax consequences cannot be determined simply because a property is described as an “office”. They depend on the parties and transaction structure. Before signing, agree the price, documents and payment arrangements with an accountant or tax adviser; see our guide to VAT when purchasing commercial property.
How to calculate a commercial mortgage: a hypothetical example
Consider a wholly hypothetical situation, unrelated to the price of F-375 or any current bank offer. The office price is ₽40 million and the appraised value is ₽36 million. Suppose that, under the chosen loan terms, the bank will finance 70% of the appraised value specifically.
The loan would therefore be ₽25.2 million: ₽36 million × 70%. The buyer would need ₽14.8 million of their own funds to pay the seller's price: ₽40 million − ₽25.2 million. This is ₽2.8 million more than 30% of the sale price. Additional costs are not included in these amounts.
If the same example assumes a hypothetical fixed interest rate of 18% per year, a term of 120 months and an annuity repayment schedule, the monthly payment would be approximately ₽454,067. With the rate unchanged, total payments over the term would be around ₽54.49 million, including approximately ₽29.29 million in interest. The calculation excludes insurance, fees and other charges; rounding and the bank's calculation method may change the schedule.
The purpose of this example is to show the relationship between the valuation, loan and buyer's funds, not to suggest a market interest-rate benchmark. For an actual purchase, request a complete repayment schedule and cost estimate. Then assess how much cash the business would retain in a normal month and during a downturn in revenue, allowing for office operating costs.
How to compare interest rates and bank offers
A rate advertised as “from” on a bank's website is not a personalised offer. Compare documents based on the same scenario: identical loan amount, term, property, buyer's funds and expected transaction date. Otherwise, an appealing figure may apply to a different borrower category or set of additional conditions.
For a fixed rate, establish whether it applies for the entire term or only a specified period, and which borrower actions could cause it to change. For a floating rate, understand the reference rate, bank's margin, reset frequency and any contractual limits on changes. The word “floating” without a clear formula does not enable you to assess the future payment burden.
- Compare repayment schedules, not just interest rates: principal repayment terms can differ.
- Check mandatory services, account and insurance requirements, fees and recurring costs.
- Clarify the procedure for partial and full early repayment, notice periods and any charges.
- Find out whether guarantees, additional collateral or maintaining particular financial ratios are required.
- Check liability for breaches and the circumstances in which the bank may demand early repayment.
For a retail programme, examine the total cost of credit disclosed by the bank and which payments it includes. For business lending, request a separate calculation of all contractual costs: consumer-lending rules cannot automatically be applied to every transaction involving a legal entity. Treat possible future refinancing as a separate scenario, not a guaranteed way to reduce costs.
Annuity repayments, equal principal repayments and a final balloon payment
With an annuity schedule, the regular payment usually remains the same if the terms are unchanged, while the proportions of interest and principal within it change. With an equal-principal schedule, principal is repaid in equal portions and interest is charged on the outstanding balance; at a fixed rate, payments gradually decrease. Comparing these offers only by the first or last month's payment is misleading.
Business financing may include deferred principal repayment or a substantial final outstanding payment, known as a “balloon”. A small regular payment in this arrangement does not mean the entire debt is being repaid evenly. Ask to see the outstanding balance at each date and separately identify the source of funds for the final payment. Do not assume that selling the office or obtaining a new loan will provide guaranteed funds.
To test affordability, prepare a monthly cash-flow plan: business receipts minus mandatory operating costs, repayments on all loans and office expenses. Recalculate it for lower receipts, a delay in making the premises operational and, for a variable rate, an increase under the contractual formula. The necessary reserve depends on these scenarios; there is no universally safe debt-service percentage for every company.
Which documents should the buyer and seller prepare?
The bank provides the exact list once the programme is identified. A generic online checklist cannot replace the requirements for the selected borrower and office. To avoid preparing documents twice, request the required contents, format and validity period of each document.
The buyer's documents
An individual may need identity documents and evidence of income, employment and existing commitments. For an individual entrepreneur or company, the bank may request registration details, financial statements, account statements and information on owners and existing loans. Where guarantors or other security providers are involved, documentation will also be needed for them.
Corporate approvals, signatory authority and necessary consents should be checked against the actual parties involved. Before applying, prepare a brief explanation of the purchase: why the business needs the office, how it will be used and which receipts are expected to service the loan.
The office's documents
Property approval may require up-to-date information from Russia's Unified State Register of Real Estate (EGRN), the documents establishing the seller's title, plans and technical information, and details of encumbrances and existing agreements. Separately confirm the requirements for the valuation report, valuer and seller's documents.
If the actual layout differs from the documentation, resolve this before final approval. The buyer should also check access to the premises, use of common areas and building systems, servicing arrangements and the components of operating charges. An attractive presentation is not enough to establish these facts.
Office due diligence: the bank does not represent the buyer's interests
A bank's review helps assess the acceptability of collateral, but it does not answer every question a future owner has. The bank focuses on repayment and security; the buyer also needs functional premises, a suitable environment for the team and predictable costs throughout ownership.
Regardless of financing approval, check the seller's authority, title history and restrictions, property documents and whether the actual condition matches the description. For a complex or high-value purchase, consider engaging qualified specialists for legal and technical due diligence. Define their tasks before commissioning the work so that you receive conclusions on specific risks, not merely a formal collection of papers.
A valuation report is also not equivalent to comprehensive transaction due diligence. It addresses value within its agreed scope. The buyer should separately review the commercial property due-diligence process before purchase and identify which questions fall outside the bank's review.
How to buy an office with a mortgage: the transaction sequence
- Identify the owner, borrower and purpose of the purchase. Agree the maximum buyer-funded amount and an affordable payment burden for the business.
- Check the office's preliminary eligibility against the bank's requirements. Provide the property's key characteristics before commissioning paid documents.
- Request comparable offers and document lists. Clarify the validity periods of decisions and the conditions for final approval.
- Complete borrower and property checks and prepare a valuation meeting the bank's requirements. Agree the loan amount once the results are available.
- Record the purchase terms with the seller. Agree how to proceed if the bank declines, the valuation changes or the loan disbursement is delayed.
- Agree the loan agreement, sale agreement, security and payment arrangements. All parties should share the same understanding of the conditions and timing for releasing funds.
- Sign the documents and complete registration steps in the agreed sequence. Clarify which evidence is needed to release funds under a letter of credit or another chosen payment arrangement.
- Document the office handover and complete the payments. Obtain the necessary records and check compliance with the bank's post-completion requirements.
Do not schedule a move based solely on preliminary loan approval. Timing depends on document readiness, property checks, registration and the parties' agreements. Any right to use the premises before payments are completed must be agreed separately, not assumed.
Risks and questions to discuss before signing
The main risk is treating the purchase decision as final before the property, loan amount and agreements have been approved. A revised valuation, unsuitable security or missing documents can change the initial budget. The earlier these issues are identified, the more scope the buyer has to adjust the terms without losing time and money.
A second risk is spending the entire available cash reserve on the purchase. Even a suitable office can place excessive pressure on the business when loan repayments, operating costs and fit-out must all be paid. With a floating rate, separately assess how higher payments would affect working capital. If the office is being bought as an investment, do not treat future income as a guaranteed source of repayment.
Before signing, ask the bank and seller the following questions:
- What remains unapproved, and which conditions must be met before the loan is disbursed?
- Which value determines the loan amount, and who pays the difference from the sale price?
- What amounts will be needed before completion, on the payment date and after buying the office?
- Can the rate change, and which formula will determine the new payment?
- What obligations do guarantors and other security providers assume?
- What happens to an advance or earnest-money deposit if financing is not obtained?
- When will the seller receive the funds, and when will the buyer acquire title and actual access to the premises?
- How will a sale of the mortgaged office, early repayment and possible changes in use be agreed?
A credit-funded purchase does not become better value than renting simply because the loan payment resembles the rent. A sound comparison requires the full ownership budget, the cost of the buyer's own funds and scenarios for using the premises. This approach is explored in “Buy or rent an office in Moscow City”.
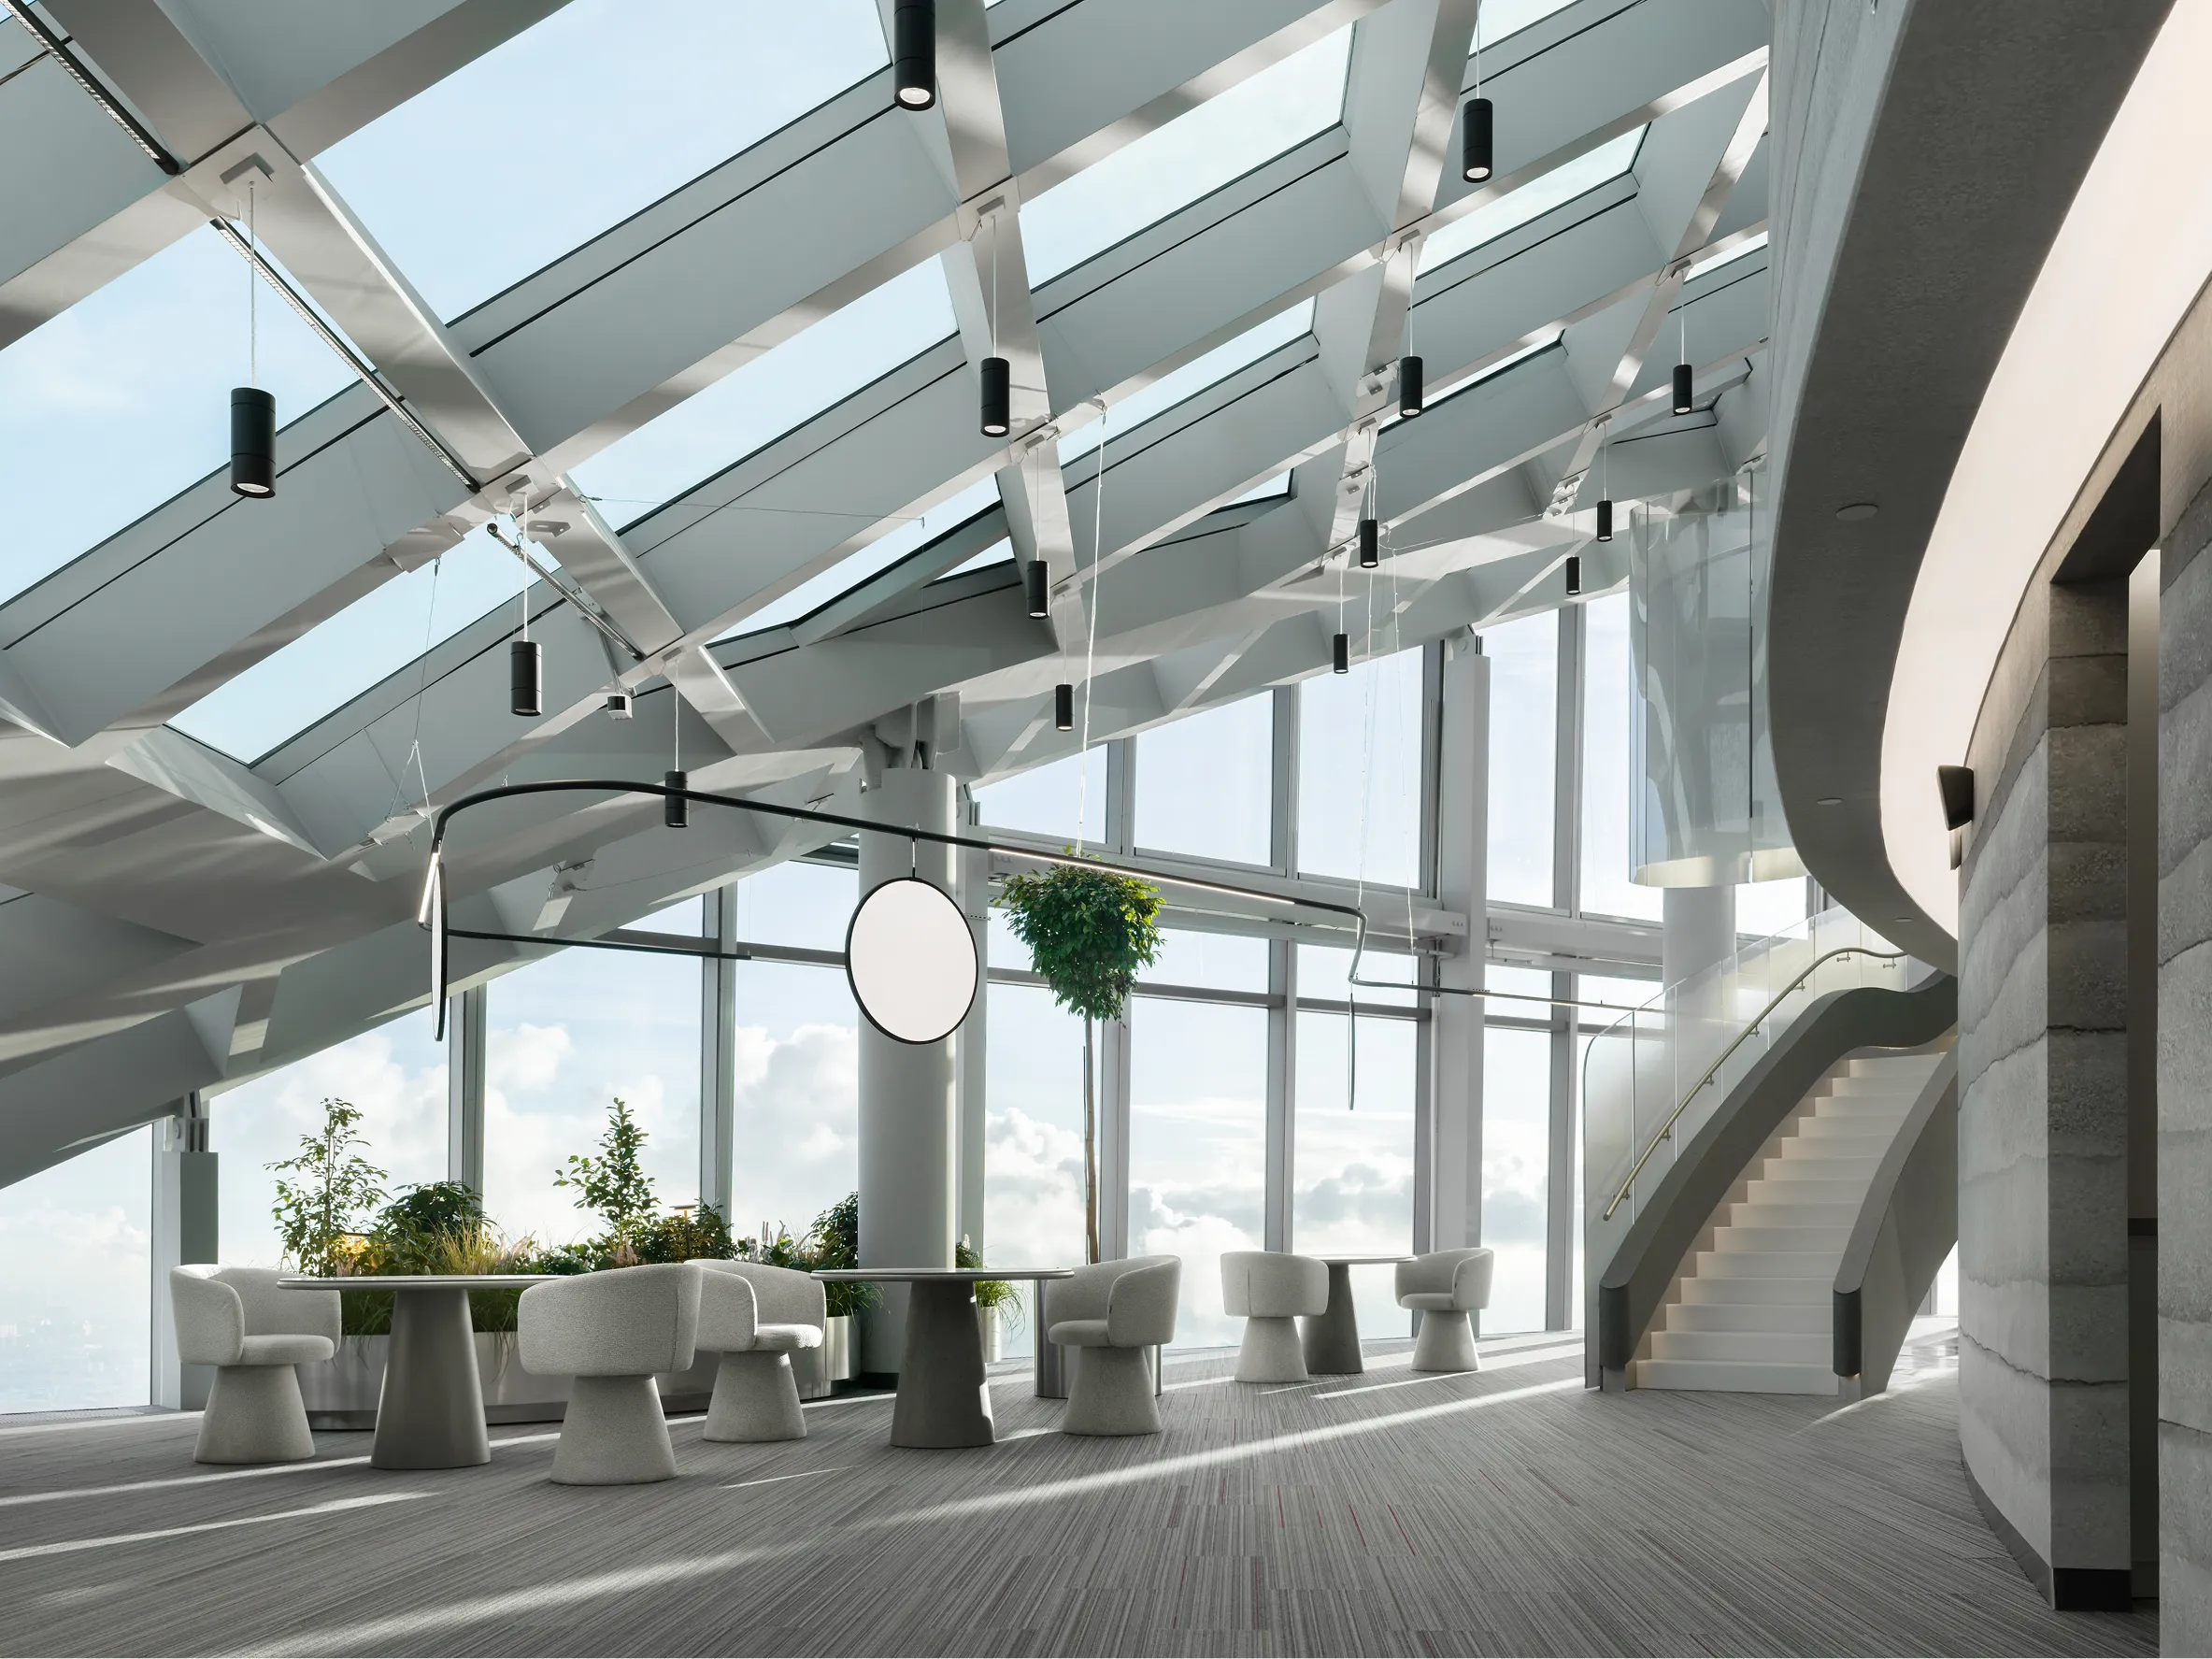
If you are considering the purchase of a prestigious corporate office, explore the F-375 office penthouse in Federation Tower and request property information for your own due diligence. Bank financing eligibility, security requirements and transaction terms are assessed individually. A property being offered for sale does not mean it automatically qualifies for every mortgage programme.
Frequently asked questions about commercial mortgages
Can an individual buy an office with a mortgage?
Yes, some banks offer non-residential property purchase programmes for individuals. However, requirements for the buyer, property type and seller vary. Check whether the particular office qualifies for the selected programme, not merely whether its name includes the word “commercial”.
Can an individual entrepreneur or an LLC obtain a commercial mortgage?
Banks offer property purchase financing for businesses. Loan eligibility depends on the programme, the borrower's activities and financial position, and the property's characteristics and security. Obtain the document list and terms for the particular individual entrepreneur or company.
How much of your own money is needed to buy an office?
You need to cover the difference between the seller's price and the loan actually approved, associated costs and the necessary reserve. There is no universal down payment amount. If the valuation is below the sale price, you may need more of your own funds than initially calculated.
Can you buy an office without a down payment?
This depends on the bank's programme, the security and its decision on the borrower. Even if no down payment is required, transaction costs and the need to retain a reserve remain. Do not assume that a no-down-payment option is available to every buyer and property.
How does the bank's valuation differ from the office price?
The price is the amount agreed between the seller and buyer. The appraised value is determined in a report according to the agreed scope and may differ from the contract price. Which value is used to calculate the loan must be checked in the particular bank's terms.
Does loan approval guarantee that you can buy the selected office?
No. In addition to assessing the borrower, the bank reviews the property and transaction documents. Preliminary approval is not the same as final financing approval for a particular office. Before paying the seller, establish the remaining conditions and consequences of rejection.
Can you repay the loan early or sell the mortgaged office?
Check the contract and agree with the bank the procedures for early repayment and transactions involving the secured property. Notice periods, documents and costs may vary between programmes. Selling a mortgaged office requires an agreed payment arrangement and process for dealing with the encumbrance in advance.
This article is for information only and does not replace individual financial, legal or tax advice. Financing and transaction terms must be checked against the current documents of the bank and the parties to the purchase.